Nasdaq Bounces as Chip Stocks Rally, Logs 3.4% Weekly Loss
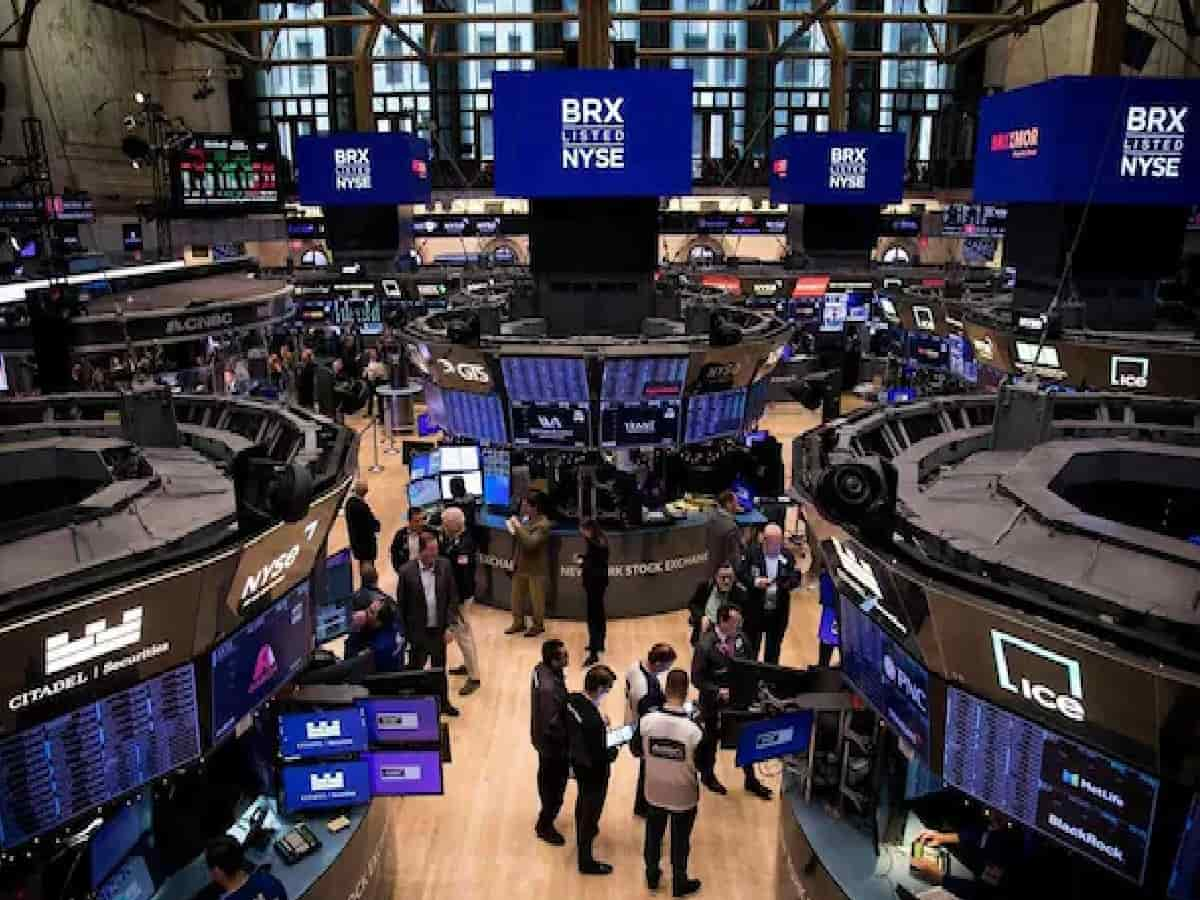
Wall Street's turbulent trading week concluded on a mixed, cautious note on Friday as aggressive bargain hunting across beaten-down semiconductor counters helped the tech-heavy Nasdaq Composite mount a partial recovery. The rebound followed Thursday's historic market route—the sharpest single-day sell-off across all three benchmark indexes since April 2025—which pushed the Nasdaq into technical correction territory and wiped nearly $1 trillion from the combined market capitalization of the "Magnificent Seven" technology giants. Dip-buyers stepped in to scoop up discounted shares of semiconductor bellwethers like Nvidia and Micron Technology, driving the Nasdaq up 1.09% to close at 24,579.42 points, while the broader S&P 500 inched up 0.31% to 7,376.86 points. However, persistent weakness in cyclical, financial, and industrial heavyweights dragged the blue-chip Dow Jones Industrial Average down 237.33 points, or 0.46%, to finish at 51,285.73 points. Despite Friday’s late-week relief rally, major US equity benchmarks booked steep weekly declines, with the Nasdaq sliding 3.4% and the S&P 500 shedding 2.7% over five volatile sessions, reflecting lingering investor anxiety over the durability of the artificial intelligence boom and shifting political dynamics in Washington.
Bargain Hunting in Tech: How Chip Giants Sparked Friday's Rebound
The turnaround in sentiment on Friday was anchored almost entirely in the semiconductor and mega-cap hardware space, where institutional investors capitalized on deeply compressed valuations following Thursday’s indiscriminate dumping. Memory chipmaker Micron Technology led the recovery charge, surging nearly 5% after enduring a brutal 17% drop in the prior session. Market bellwether Nvidia advanced roughly 3%, a move that pulled the AI chip designer back into positive territory on a year-to-date basis and injected confidence across the broader electronics supply chain. Other technology stalwarts, including electric vehicle maker Tesla, social media conglomerate Meta Platforms, and Google parent Alphabet, also posted solid gains as portfolio managers selectively rebuilt long positions.
Yet market strategists caution that Friday's selective buying does not necessarily signal an immediate end to broader technology volatility. Stuart Clark, portfolio manager at Quilter, highlighted to CNBC that the increasing reliance of benchmark indexes on a narrow cluster of mega-cap technology and semiconductor firms poses structural risks for the wider market. When market capitalization becomes heavily concentrated in names like Nvidia, Apple, and Microsoft, any fundamental stumble or multiple compression in those leaders triggers outsized collateral damage across both the Nasdaq and the S&P 500. While value-seeking investors capitalized on short-term oversold conditions on Friday, institutional capital remains circumspect about committing fresh money until broader regulatory and geopolitical clouds dissipate.
Anatomy of Thursday's Rout: The $1 Trillion Magnificent Seven Wipeout
To understand Friday's tentative stabilization, investors must examine the extraordinary wreckage of Thursday's trading session, which shattered months of low volatility across American equity desks. All three major indexes suffered their worst single-day percentage declines in more than a year and a half. The Nasdaq Composite plunged an eye-watering 5.5%, falling more than 10% below its recent peak and officially crossing into technical correction territory. The benchmark S&P 500 slumped 4.4% in a broad-based liquidation that left all 11 of its constituent sectors in negative territory, while the 30-stock Dow Jones Industrial Average plunged over 1,800 points, or 3.4%.
The sheer magnitude of the drawdown erased an estimated $1 trillion in shareholder value from the elite "Magnificent Seven" cohort in a span of just six and a half trading hours. Algorithmic execution desks and risk-parity funds triggered cascading stop-loss liquidations across tech portfolios as traders rushed to hedge against downside risks. Analysts noted that the velocity of the decline underscored how stretched equity valuations had become following prolonged multiple expansion throughout 2026, leaving growth stocks exceptionally fragile in the face of unexpected macroeconomic or legislative shocks.
Political Headwinds: Midterm Fallout and Texas Data Center Uncertainty
The fundamental catalyst that ignited the market's retreat was an abrupt reassessment of political and regulatory risk following the outcome of the US midterm elections. Sweeping victories by the Democratic Party across both chambers of Congress and key gubernatorial races introduced immediate legislative uncertainty for corporate America, particularly for companies tied to energy-intensive artificial intelligence infrastructure. Investors had previously priced in a regulatory environment favorable to fast-tracked energy permits and corporate tax stability; the political shift prompted swift repricing across speculative growth sectors.
Of immediate concern to technology investors are mounting political headwinds confronting hyperscale data center construction across the United States. In Texas, which has rapidly transformed into the nation's preeminent computing hub due to its deregulated power market and vast land availability, Governor-elect Gina Hinojosa signaled that state authorities should pause active data center permitting until comprehensive safety, grid resilience, and environmental legislation is enacted. Because hyperscale data centers demand enormous baseload electricity and cooling infrastructure, regional scrutiny over grid reliability and local utility rates has reached a boiling point. Market analysts emphasize that this regulatory ambiguity is unlikely to resolve until newly elected legislative bodies and governors assume office in January, creating a multi-month overhang for capital expenditure plans across cloud infrastructure providers.
Strong Jobs Data Offsets Microsoft Cloud Jitters
Adding to Friday's mixed trading environment were corporate developments inside software giant Microsoft that temporarily checked technology gains. Reports surfaced via CNBC indicating that Microsoft is actively planning to reduce its roster of third-party "neo-cloud" partner providers, a move aimed at rationalizing infrastructure spending and prioritizing its internal Azure ecosystem. The prospective consolidation raised immediate questions across trading desks regarding forward revenue runways for smaller, specialized cloud computing vendors and contracted data center operators that rely on mega-cap enterprise contracts.
However, the drag from cloud concerns was counterbalanced by a surprisingly robust macroeconomic report from the labor market. The US Department of Labor’s October non-farm payrolls data revealed that the domestic economy added 165,000 jobs, comfortably outpacing consensus forecasts from Wall Street economists who had projected an increase of approximately 59,000 payrolls. Furthermore, the national unemployment rate dipped to 4.1%, beating projections that anticipated it would remain steady at 4.2%. The robust labor figures provided reassurance that underlying consumer spending power and economic activity remain resilient, partially dampening fears that an aggressive tech sell-off could spill over into broader systemic economic weakness.
Wall Street's Weekly Scorecard: What Lies Ahead for Global Investors
Despite the relief provided by Friday’s chip-driven bounce, the cumulative weekly score sheet left all three major US indexes nursing substantial bruises. For the week, the Nasdaq Composite shed 3.4%, the S&P 500 dropped 2.7%, and the Dow Jones Industrial Average logged a 0.9% decline. The retreat marks a pivotal juncture for institutional asset allocators, who are increasingly rotating capital away from semiconductor names trading at high price-to-earnings multiples and into cash-generative value sectors, healthcare, and emerging markets where domestic demand shields balance sheets from Silicon Valley capital expenditure cuts.
As global markets digest the weekly fallout, trading desks will turn their attention to upcoming inflation readings, corporate earnings reports from enterprise software firms, and clarity from Washington regarding post-election legislative priorities. The sudden swing from euphoria to volatility serves as a reminder that even the most transformative secular themes, such as artificial intelligence, cannot remain completely decoupled from regulatory frameworks, electrical grid constraints, and macroeconomic fundamentals. For investors navigating this volatile landscape, disciplined portfolio diversification and rigorous balance-sheet vetting will remain critical as equity markets search for a durable floor heading into the final stretch of 2026.