IndiGo Shares Surge 4% to Hit ₹4,868 as Nomura, Jefferies & HSBC
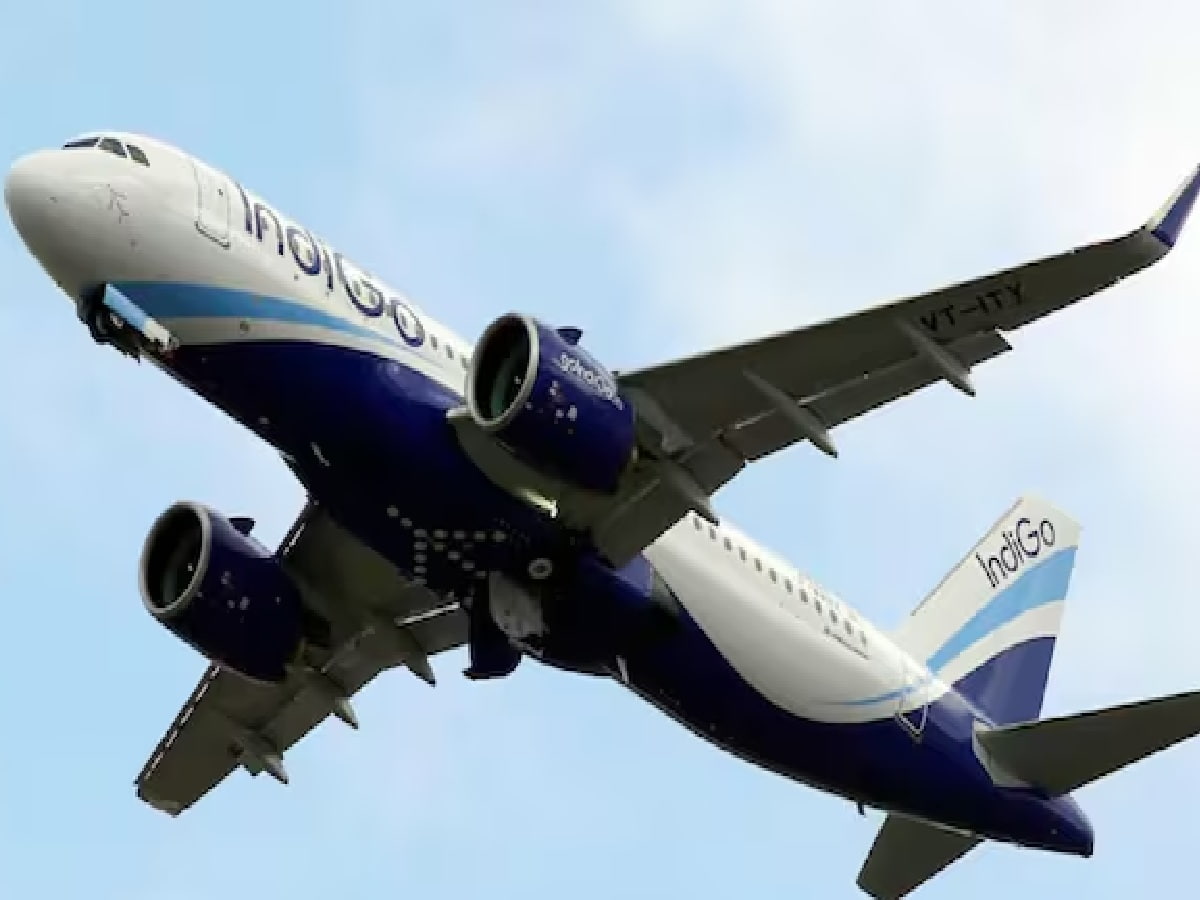
Shares of InterGlobe Aviation, the operator of India’s leading carrier IndiGo, rebounded sharply from opening lows on Friday morning, October 30, 2026, jumping over 4 percent to record an intraday peak of ₹4,868 on Dalal Street. The surge followed the airline's post-market September quarter (Q2 FY27) financial scorecard, which showcased strong double-digit top-line growth and a marked improvement in operational margins, effectively reassuring investors despite broader concerns over escalating aviation turbine fuel (ATF) expenditures and sequential profitability headwinds. Fueling the market optimism, top global institutional brokerages Nomura, Jefferies, and HSBC maintained high-conviction 'Buy' ratings on the aviation counter, with Nomura raising its target price to a Street-high ₹6,200 on the back of resilient passenger yields, superior cost pass-through capabilities, and robust festival and winter travel booking visibility.
Bullish Brokerage Verdicts: Nomura Eyes ₹6,200 as Yields Cushion Fuel Shocks
Global research houses largely commended IndiGo's disciplined capacity deployment and resilient passenger revenue per available seat kilometer (PRASK), viewing strong ticket realization as an effective shield against higher input expenses. Nomura reiterated its 'Buy' recommendation with an upgraded price target of ₹6,200, highlighting that the airline's second-quarter operating EBITDA beat consensus estimates and forecasting that IndiGo can successfully pass on 80 to 90 percent of escalated jet fuel costs directly to air travelers through firm base fares, prompting the brokerage to lift its FY27 and FY28 EBITDA forecasts by 11 percent and 3 percent, respectively. Meanwhile, Jefferies maintained a 'Buy' rating with a target of ₹5,650, noting that while operational numbers were slightly subdued, a 34 percent year-on-year rise in ticket fares successfully softened cost impacts, alongside management guidance pointing to single-digit capacity expansion and a PRASK increase exceeding 25 percent in the third quarter, though it adjusted FY27 and FY28–29 EPS projections marginally lower by 9 percent and 2 percent. Similarly, HSBC posted a 'Buy' rating with a target price of ₹5,545, emphasizing that Q2 EBITDA surpassed its internal estimates by 25 percent, while projecting full-year PRASK growth above 25 percent and highlighting the airline's strategic pivot toward boosting cargo business and ancillary service monetization to offset a high single-digit rise in non-fuel unit costs.
Q2 Earnings Breakdown: Revenue Climbs 25.9% to ₹23,364 Crore as Forex Losses Narrow
IndiGo’s core operational metrics underscored sustained domestic and international air travel demand, with total revenue from operations advancing 25.9 percent year-on-year to ₹23,364 crore during the September quarter, up from ₹18,555.3 crore recorded in the corresponding quarter of the previous fiscal. The airline's operational efficiency was further reflected in its earnings before interest, taxes, depreciation, amortization, and rental (EBITDAR), which more than doubled to ₹2,460 crore from ₹1,114.3 crore a year earlier, driving EBITDAR margins up from 6 percent to 10.5 percent. The balance sheet also benefited from a substantial reduction in foreign exchange volatility, with net forex losses shrinking to ₹1,333 crore compared to ₹2,892 crore reported in Q2 of the prior year. However, crude-linked cost escalation remains a critical variable for Dalal Street to monitor, as fuel cost per available seat kilometer (ASK) climbed 68.9 percent to ₹2.44, reinforcing management's ongoing focus on high-yield load factors, fleet fuel efficiency, and route optimization entering the peak festive third quarter.