Ather Energy Surges 7% on Maiden Net Profit; Nomura Names It Top 2W Pick
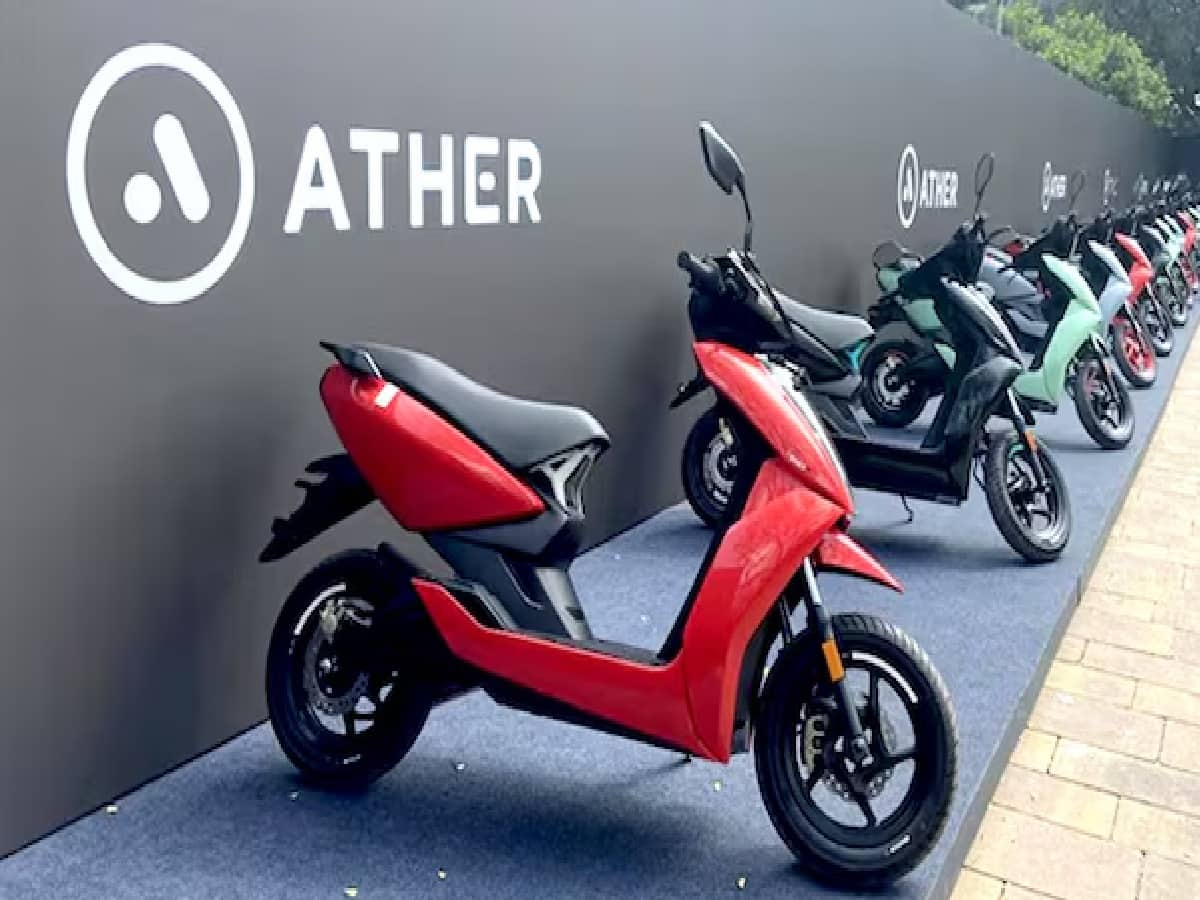
Marking a historic operational turning point for India's clean mobility sector, shares of electric two-wheeler manufacturer Ather Energy surged by over 7% during intraday trade on Tuesday, October 27, 2026, following the announcement of its second-quarter financial results for fiscal year 2026-27 (Q2 FY27). The Bangalore-based EV pioneer achieved profitability for the first time in its corporate history, posting a consolidated net profit of ₹1.26 crore against a steep net loss of ₹154 crore reported during the corresponding quarter of the previous fiscal year. Underpinned by surging consumer adoption and manufacturing scale, operational earnings underwent a dramatic reversal as EBITDA flipped into the black at ₹11.3 crore compared to an operational loss of ₹133 crore twelve months earlier. Total top-line revenue for the September quarter expanded by a robust 62.8% year-on-year to touch ₹1,464 crore, climbing sharply from ₹899 crore in Q2 FY26, as quarterly retail deliveries climbed 42% to reach an unprecedented volume milestone of 93,000 electric scooters.
Nomura Crowns Ather Top Pick at ₹2,070 as HSBC Raises Target to ₹1,800
The turnaround triggered immediate bullish upgrades from premier global investment banks, with Japanese brokerage Nomura maintaining its Buy recommendation, elevating Ather Energy as its definitive "top pick" across the Indian two-wheeler space, and assigning an aggressive target price of ₹2,070 per share. Nomura highlighted that Ather’s reported EBITDA margin of 0.8% decisively outpaced street expectations, beating the brokerage's own projection of -2.6% and the broader consensus estimate of -2.7% on the back of resilient average selling prices (ASPs), strong customer bookings, and expanding gross margins. The brokerage observed that the market introduction of the new Konarc electric scooter lineup has materially improved multi-year revenue visibility, terming Ather’s valuation attractive at 4 times its estimated FY29 Enterprise Value-to-Sales (EV/Sales) multiple given its superior volume growth relative to legacy internal combustion engine (ICE) peers. Concurrently, global banking group HSBC reaffirmed its Buy rating and raised its target price on Ather to ₹1,800, emphasizing that achieving operational EBITDA breakeven amid elevated raw material input prices underscores strong structural cost control, while cautioning that consumer reception and sustained conversion rates for the Konarc platform will serve as the primary near-term monitoring metric.
Scaling to 1.14 Million Units: Dual-Plant Expansion Across Hosur and Maharashtra
To service accelerating demand and fortify its national supply chain, Ather Energy’s board of directors formally approved extensive capacity expansion programs across its primary manufacturing clusters in Hosur, Tamil Nadu, and Chhatrapati Sambhajinagar, Maharashtra. Under the approved capital expenditure roadmap, the Hosur plant is on track to commission an additional monthly throughput of 6,000 units within the ongoing quarter. Simultaneously, the state-of-the-art greenfield facility in Chhatrapati Sambhajinagar is scheduled to initiate trial production runs for Phase 1 over the coming weeks, with full equipment installation and capital outlays targeted for finalization by the fourth quarter of FY27. This Western India facility is engineered to inject an incremental monthly output of 12,500 scooters by the second quarter of FY28, progressively elevating Ather Energy's cumulative annual installed manufacturing run-rate to 1.14 million units, cementing its industrial foundation to capture mainstream two-wheeler market share.