US Midterm Results Trigger Futures Slump: S&P 500 Could Rally 14% Next Year
Initial trends in the 2026 United States midterm elections indicating strong momentum for the Democratic Party have sent immediate shockwaves through global financial markets, triggering a sharp pullback in equity futures and the US dollar. As prediction platforms and counting centers pointed to a possible shift in congressional control, investors recalibrated their portfolios to price in policy friction in Washington. However, comprehensive market data spanning more than four decades suggests that immediate post-election volatility rarely dictates long-term performance. According to historical tracking by CNBC, the benchmark S&P 500 has consistently generated an average return of 13.7 percent in the twelve-month period following midterm elections, demonstrating that systemic economic strength and the dissipation of electoral uncertainty matter far more to equity valuations than which party controls Capitol Hill.
Global Market Volatility: Nasdaq Futures Slide 2% as Dollar Weakens and Yields Drop
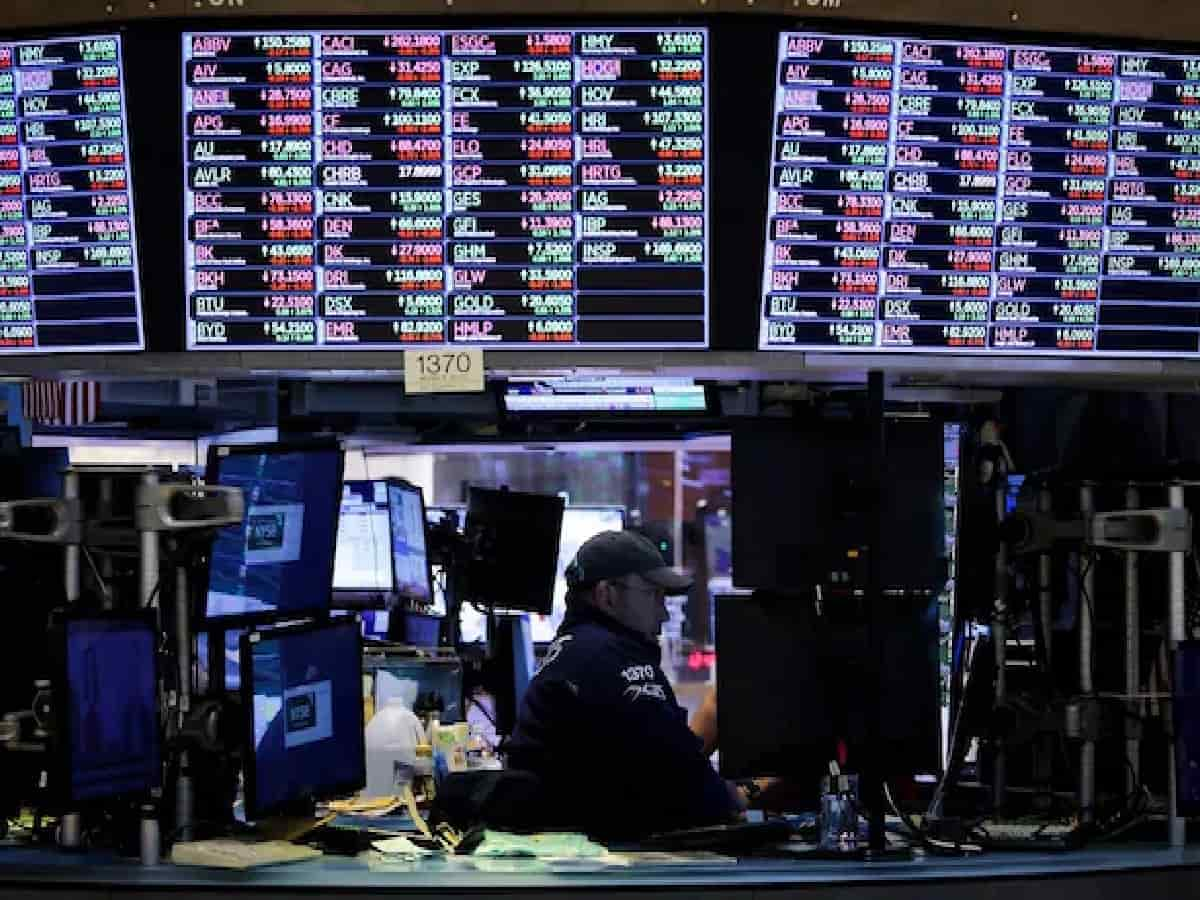
The initial reaction across global trading desks was swift as traders reacted to the prospective shift in legislative power. S&P 500 futures abruptly reversed an early 0.5 percent advance to sink 0.7 percent into negative territory, while the tech-heavy Nasdaq 100 futures absorbed the brunt of the sell-off, tumbling approximately 2 percent. The greenback experienced broad-based selling pressure, retreating against every major currency in the G-10 basket as currency markets adjusted expectations for federal spending and regulatory oversight. Concurrently, bond traders sought safe-haven assets, driving the yield on the benchmark 10-year US Treasury note down by 6 basis points to 4.91 percent. The risk-off sentiment swiftly crossed over into international sessions, dragging the MSCI Asia Pacific Index lower by 0.5 percent during early regional trading.
Historical Precedent: The Post-Midterm Relief Rally and the S&P 500 Track Record
While immediate post-poll trading often reflects knee-jerk anxiety, historical analyses of elections from 1980 through 2024 present an overwhelmingly optimistic trajectory for patient investors. Following midterm balloting, the S&P 500 has posted average gains of 0.2 percent over both the one-day and one-week horizons, expanding to an average monthly increase of 1.1 percent. Over a full one-year timeframe, returns expand dramatically: the S&P 500 has delivered an average gain of 13.7 percent following midterm cycles and 13.8 percent following presidential contests, closing in positive territory in 91 percent of all election cycles. Remarkably, across all 11 midterm elections held between 1982 and 2022, the index recorded absolute gains one year later without exception. Addressing this historical resilience, Carson Group Chief Market Strategist Ryan Detrick observed that equity markets typically experience a relief rally once electoral ambiguity subsides, allowing corporate executives and institutional allocators to deploy capital with clear visibility.
The Gridlock Advantage: Why Divided Government Fuels 15% Wall Street Rallies
A deeper look at parliamentary configuration reveals that Wall Street frequently favors institutional stalemate over unified single-party dominance. Historical review shows that when executive authority in the White House is balanced against an opposition-controlled House or Senate, legislative inertia prevents radical fiscal overhauls, sweeping tax hikes, or drastic regulatory swings. Across 15 presidential and midterm election cycles that produced a divided government, the S&P 500 generated an average annual return of 15 percent, finishing with positive gains in 14 of those 15 instances. By contrast, under unified government conditions where one party controlled both the White House and Capitol Hill, the index recorded a lower average annual return of 11.5 percent. Even in historical scenarios directly mirroring the current cycle—such as the midterm elections of 1986, 1990, and 2006, where a Republican president faced a newly elected Democratic Congress—the S&P 500 dipped just 0.5 percent on day one before rebounding 3.4 percent within a month and accelerating to a 10.9 percent gain over the following year.
Macro Fundamentals Prevail: From the Dot-Com Bust to the 2020 Liquidity Surge
Despite the historical patterns surrounding electoral politics, financial strategists emphasize that macroeconomic fundamentals, central bank monetary policy, and corporate earnings ultimately steer the market’s trajectory. The 2000 election cycle provides a stark case study: despite the political resolution, the collapsing dot-com bubble dragged the S&P 500 down by 22.1 percent over the ensuing twelve months, marking its steepest post-election retreat since 1980. Conversely, following the 2020 election, an unprecedented influx of fiscal stimulus, low borrowing costs, and pandemic economic reopening propelled the index to a 38.3 percent rally over the next year, representing its strongest post-election performance in more than four decades. While the initial reaction to the 2026 midterm results has weighed on short-term sentiment, long-term market direction will remain governed by underlying macroeconomic indicators, labor market stability, and corporate profitability.