NSE Shares Make Market Debut, Brokerages See Long-Term Growth Potential
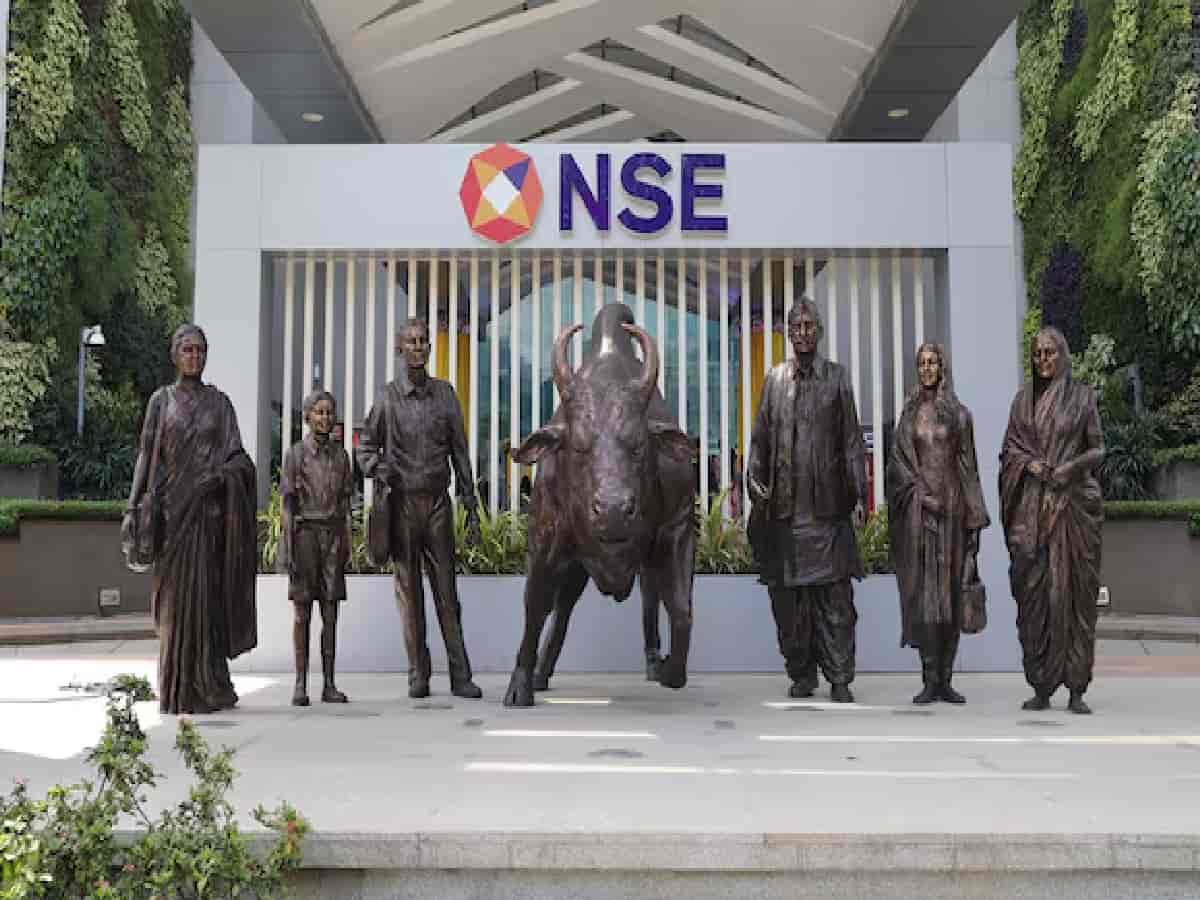
Shares of the National Stock Exchange of India (NSE) marked a historic entry onto Dalal Street on Thursday, listing at ₹1,800 per share, reflecting a modest premium over the IPO issue price of ₹1,785. Robust buying interest immediately followed the opening bell, propelling the stock to an intraday high of ₹1,878. As trading transitioned into the final hour, the shares hovered near ₹1,825. At its session peak, the exchange operator vaulted into the elite club of India's corporate heavyweights, ranking as the country's ninth most valuable company by market capitalization and surpassing household leaders Hindustan Unilever Limited (HUL) and Sun Pharma. The company’s total market valuation crossed the milestone of ₹4.51 lakh crore on day one, prompting major domestic and global brokerage houses to immediately initiate active research coverage with bullish price objectives.
Macquarie Tags NSE as 'The Dominator' with ₹1,965 Target
Global brokerage firm Macquarie initiated coverage on NSE with an 'Outperform' recommendation and a 12-month target price of ₹1,965 per share, representing an upside potential of approximately 10 percent from the upper end of the IPO price band. In its investment note titled 'The Dominator', Macquarie emphasized that NSE holds an unassailable leadership position in India's capital market architecture. The brokerage highlighted the exchange's commanding market share across cash and derivatives segments, an extensive multi-asset product suite, cutting-edge low-latency technology infrastructure, and unmatched deep liquidity pools. Describing the exchange as an indispensable beneficiary of the ongoing financialization of domestic household savings, Macquarie pointed to self-reinforcing network effects, superior operating margins, and strong free cash flow generation as long-term defensive moats.
Emkay Sets Street-High Target of ₹2,050 on Capital Market Expansion
Domestic research firm Emkay Global Financial Services came out with a 'Buy' recommendation, setting the Street-high target price of ₹2,050 based on September 2027 earnings projections, representing an upside of around 15 percent. Emkay's thesis centers on the structural expansion of India’s retail investor base, expanding mutual fund inflows, and broader wealth creation. The brokerage noted that India remains in the early chapters of financial asset allocation, positioning the primary exchange infrastructure to capture exponential volume expansion over the next decade as corporate equity funding and institutional participation deepen across tier-2 and tier-3 cities.
PL Capital Assigns 'Accumulate' Rating with ₹1,950 Target on Revenue Diversification
Initiating coverage with an 'Accumulate' rating, domestic brokerage PL Capital assigned a target price of ₹1,950 for the stock, indicating an upside of more than 9 percent over the issue band. PL Capital noted that transaction income generated 79 percent of NSE's total operating revenue in FY26. However, the brokerage forecasts an important structural shift in the exchange's financial model, with revenue streams becoming significantly more balanced through FY29. High-margin non-transaction business segments—including listing fees, co-location server rack infrastructure, real-time market data feeds, and index licensing—are projected to expand at a compound annual growth rate (CAGR) of around 14 percent between FY26 and FY29, outpacing core transaction revenue growth projected at a 9 percent CAGR.