NSE Shares: Heavy Profit-Taking Drags Debutant to ₹1,774
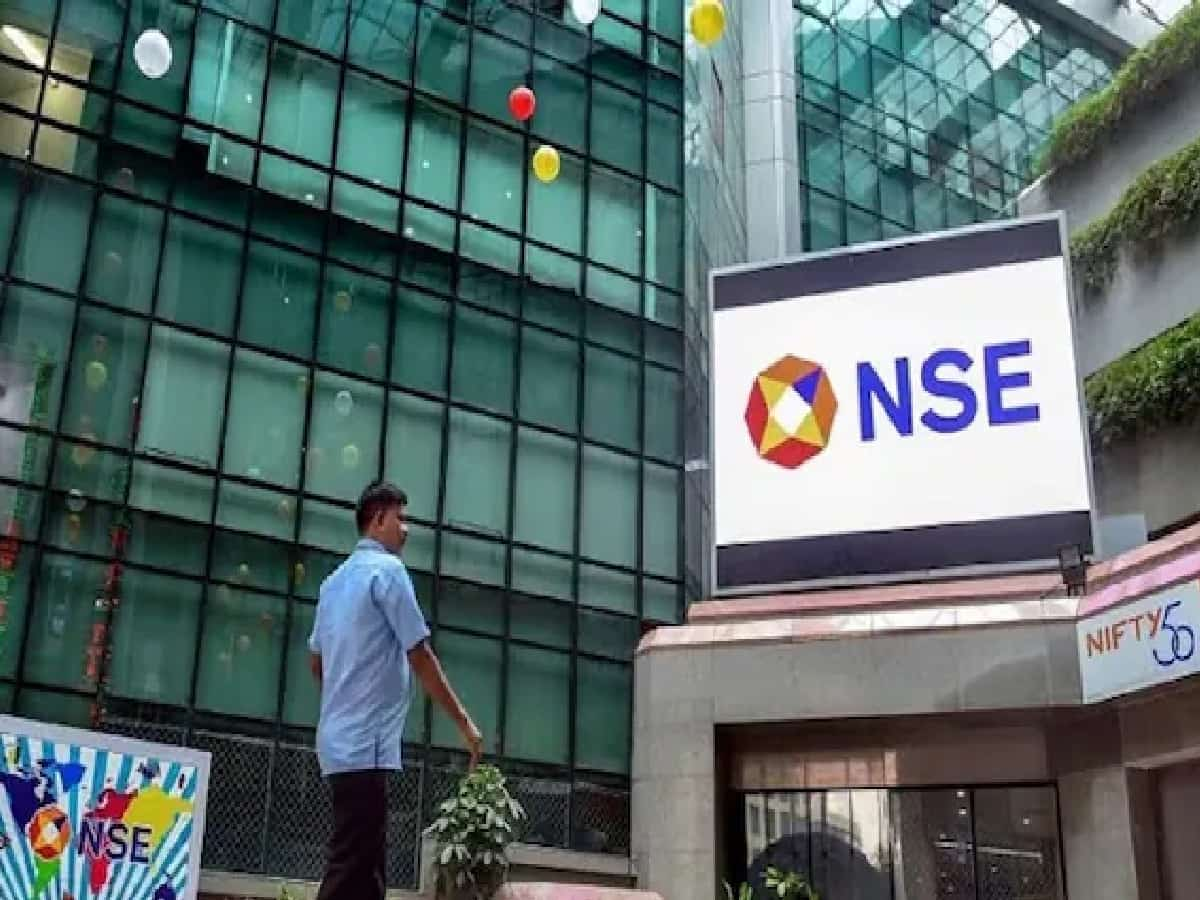
In a surprising post-listing trajectory for one of Dalal Street's most anticipated public issues, the shares of the National Stock Exchange of India (NSE) dipped below their initial issue price on Monday, September 28, 2026. Trading on rival bourse BSE—to comply with regulatory conflict-of-interest mandates—NSE equity slipped to ₹1,774 by midday, falling ₹11 below the upper price band allotment price of ₹1,785. The counter experienced a 1.04 percent intraday drop from Friday’s close of ₹1,792.65, translating to an aggregate 5.5 percent retracement from its opening-day high of ₹1,878. While morning weakness across benchmark indices Sensex and Nifty added broader market pressure, institutional selling and post-debut profit booking emerged as primary drivers behind the rapid cooldown.
From Day One Highs to Quick Consolidation: Price Action Since Debut
The mega initial public offering, structured entirely as an Offer for Sale (OFS) aggregating ₹22,569 crore, had witnessed robust subscription demand of 5.71 times, led aggressively by qualified institutional buyers. However, market reception post-listing reflected sharp profit-taking rather than sustained runaway momentum. Debuting on September 24 at ₹1,800—a modest 0.84 percent listing premium—the stock surged intra-day to reach ₹1,878 before settling at ₹1,818 as institutional sellers pared holdings. On day two, Friday, the counter opened at ₹1,825 but retreated to close at ₹1,792.65, demonstrating that despite overwhelming primary-market bidding, secondary-market pricing quickly adjusted to supply-demand dynamics and immediate liquidity clearing.
Valuation Headwinds: 43x P/E Multiple Debated Against Macquarie's ₹1,965 Target
Market participants continue to scrutinize the bourse operator's long-term valuation metrics, with NSE commanding a market capitalisation of approximately ₹4.44 lakh crore at current levels. This capitalization values the exchange at roughly 43 times its FY2026 price-to-earnings (P/E) multiple, leading several domestic market analysts to label entry valuations expensive in light of potential volume cyclicality in derivatives and cash market turnover. Conversely, global brokerage Macquarie maintained a positive fundamental view, assigning a 12-month target price of ₹1,965 per share on expectations of enduring market dominance and structural financialization trends across India. As secondary market volatility normalizes, investor attention will pivot toward quarterly transaction revenue run-rates, regulatory compliance overheads, and underlying volume growth to establish sustained price support.